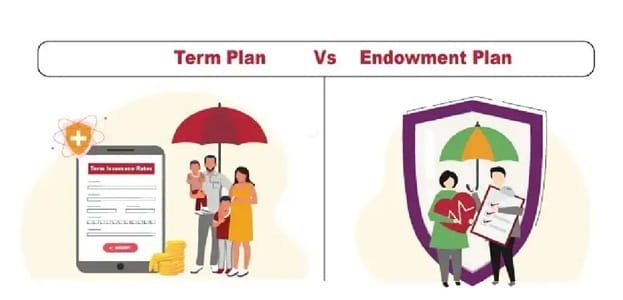
Term life insurance and endowment insurance are both life insurance products, but they are designed for very different financial goals. A term plan primarily protects the family against the financial impact of the policyholder’s death, while an endowment plan combines life insurance with long-term savings.
This difference affects almost everything: premium, maturity value, sum assured, liquidity and expected financial outcome.
A buyer who mainly wants large life cover at an affordable premium will generally find term insurance more suitable. Someone who wants insurance along with a disciplined savings element may consider an endowment plan, provided the premium fits comfortably into the long-term budget.
LIC’s current product portfolio itself separates pure term assurance plans from endowment plans, reflecting these very different purposes.
What Is Term Life Insurance?
Term life insurance provides protection for a specified policy period.
Suppose you purchase:
- Sum assured: ₹1 crore
- Policy term: 30 years
If the insured person dies during those 30 years while the policy is in force, the nominee receives the applicable death benefit.
Under a pure term insurance plan, there is normally no maturity value if the insured survives the policy term.
Current LIC term products, for example, are specifically described as pure protection plans, with options in some products for level or increasing sum assured.
What Is an Endowment Insurance Plan?
An endowment policy combines:
Life insurance protection + savings benefit
The policy normally pays a benefit:
- On death during the policy term, or
- On survival until maturity
LIC’s insurance glossary describes an endowment policy as one where the insured amount becomes payable at the end of the specified period or on earlier death, according to policy conditions.
Some endowment plans may also include:
- Guaranteed additions
- Bonuses in participating products
- Surrender value
- Policy loan facility
The exact benefits vary from product to product.
Term Insurance vs Endowment Insurance at a Glance
| Feature | Term Insurance | Endowment Insurance |
| Main purpose | Life protection | Protection plus savings |
| Death benefit | Yes | Yes |
| Maturity benefit | Usually no in pure term plan | Usually yes |
| Premium for same cover | Much lower | Much higher |
| Sum assured affordability | Usually high | Usually lower for same premium |
| Savings component | No | Yes |
| Surrender value | Usually not in pure term plans | Commonly available after conditions are met |
| Policy loan | Usually no | Often available after surrender value develops |
| Best suited for | Income protection | Conservative long-term savings plus insurance |
1. The Biggest Difference Is the Premium
Term insurance is generally much cheaper for the same amount of life cover because most of the premium is used to provide mortality protection.
For example, suppose a 35-year-old wants ₹1 crore of life cover.
A pure term plan may provide ₹1 crore protection at a relatively modest annual premium.
Trying to obtain the same ₹1 crore death cover through a traditional endowment plan could require a substantially higher premium because part of the premium also supports the maturity and savings benefits.
The actual premium depends on factors such as:
- Age
- Health
- Smoking status
- Policy term
- Sum assured
- Premium payment term
The important point is that comparing a ₹1 crore term policy with a ₹10 lakh endowment policy purely by annual premium is misleading because they provide very different levels of protection.
2. Term Plans Usually Provide Much Higher Life Cover
The primary purpose of life insurance should be to replace the financial contribution of the insured person.
Suppose a family’s estimated protection requirement is ₹1.5 crore.
A term plan can make this level of cover financially practical for many working families.
With an endowment plan, the premium for the same ₹1.5 crore protection could be much higher.
This is why term insurance is commonly better suited for:
- Family income replacement
- Home loan protection
- Children’s future expenses
- Financial protection for a dependent spouse
3. Endowment Plans Provide a Maturity Benefit
The biggest attraction of an endowment plan is that the policyholder can receive money even after surviving the entire policy term.
Depending on the particular plan, maturity benefits may consist of:
- Basic sum assured on maturity
- Guaranteed additions
- Vested bonuses
- Final additional bonus where applicable
For example, LIC’s current New Endowment Plan provides maturity and death benefits and may also participate in profits through applicable bonuses according to its terms.
Term plans generally do not provide this savings component unless specifically structured as a return-of-premium product.
4. Are Endowment Returns Guaranteed?
Not necessarily in full.
Some endowment plans are non-participating and provide clearly specified guaranteed benefits.
Other participating plans may include:
- Guaranteed elements, and
- Non-guaranteed bonuses linked to insurer performance.
Therefore, buyers should distinguish between:
Guaranteed maturity amount
and
Projected maturity amount based on assumed future bonuses
Do not purchase an endowment policy simply because an illustration shows an attractive future value. Check which portions are actually guaranteed.
5. Endowment Plans Can Develop a Surrender Value
A policyholder may sometimes need to discontinue an endowment plan before maturity.
Traditional savings policies can acquire a surrender value after the required premium conditions are met.
Under IRDAI’s current rules, non-linked savings products must comply with prescribed surrender-value provisions.
LIC’s current New Endowment Plan, for example, allows surrender after completion of the first policy year if one full year’s premium has been paid, while the Guaranteed Surrender Value becomes available after at least two full years’ premiums under the current product terms.
However, surrendering early can produce a value significantly below the total premiums expected over the full policy term.
6. Policy Loans Are More Common With Endowment Plans
One useful feature of traditional savings policies is the possibility of borrowing against the surrender value.
IRDAI currently requires non-linked savings products that offer surrender value to provide a policy-loan facility based on eligible surrender value.
For example, LIC’s current New Endowment Plan allows loans after completion of the first policy year and payment of one full year’s premium, subject to limits linked to surrender value.
Pure term insurance usually does not build surrender value, so there is normally nothing against which a policy loan can be granted.
7. Which Plan Is Better for Investment?
Term insurance should not generally be viewed as an investment. It is primarily financial protection.
Endowment insurance does provide a savings element, but buyers should compare its expected long-term return with alternatives such as:
- Public Provident Fund
- Fixed-income investments
- Mutual funds
- Other long-term investments appropriate to risk tolerance
The correct comparison is not:
“Term gives nothing back, endowment gives money back.”
A better question is:
“How much life cover do I need, and what is the best way to invest the money remaining after buying adequate protection?”
For many families, separating insurance from investment can provide greater flexibility.
8. What Happens If You Stop Paying Premiums?
The effect can differ significantly.
Term Insurance
If premiums are not paid within the permitted grace period and the policy lapses, life cover can cease according to the policy terms.
Because protection is the primary benefit, allowing a term plan to lapse can leave dependants exposed.
Endowment Insurance
Depending on how many premiums have already been paid, the policy may:
- Lapse
- Become paid-up with reduced benefits
- Acquire surrender value
The exact rules vary between products.
LIC’s current New Endowment Plan, for example, provides reduced paid-up benefits once the applicable premium conditions have been met.
9. Tax Treatment
Eligible life insurance premiums can qualify for deduction under Section 80C, within the combined ₹1.5 lakh limit and subject to applicable conditions where the taxpayer is using the tax regime that permits the deduction.
Maturity taxation requires more attention for endowment policies.
For non-ULIP life insurance policies issued on or after April 1, 2023, current tax rules generally restrict Section 10(10D) exemption where annual premium exceeds ₹5 lakh, subject to aggregation and other conditions. Importantly, this high-premium restriction does not apply to amounts received on death.
Term insurance normally creates fewer maturity-tax questions because pure term plans usually do not pay a survival benefit.
10. Which Plan Should a Family Choose?
Consider Term Insurance If:
- Your family depends on your income.
- You have significant loans.
- You need ₹1 crore or more of affordable protection.
- Your priority is financial security rather than maturity value.
- You prefer investing separately.
Consider Endowment Insurance If:
- You want insurance combined with disciplined savings.
- You prefer relatively predictable benefits.
- You can comfortably maintain a higher premium for many years.
- You value policy-loan and surrender-value features.
- You understand that life cover for the same premium may be considerably lower.
Can You Own Both?
Yes.
Term and endowment insurance are not mutually exclusive.
A person may already have an endowment policy purchased years ago but still find that the death cover is insufficient for current family responsibilities.
Instead of automatically surrendering the existing policy, the person may consider adding a separate term plan to close the protection gap.
For example:
- Existing endowment cover: ₹10 lakh
- Actual life-cover requirement: ₹1.25 crore
- Additional term insurance required: approximately ₹1.15 crore
This can preserve the existing savings policy while improving family protection.
Conclusion
Term insurance is primarily for protecting family income, while endowment insurance combines life cover with long-term savings. For most buyers, the first priority should be adequate life protection. Savings features should be considered only after confirming that the policy provides enough cover and that its long-term premium remains affordable.
FAQs
1. Is term insurance always better than an endowment plan?
No. They solve different problems. Term insurance is generally better when maximum life protection at an affordable premium is the priority. Endowment insurance may suit someone who deliberately wants savings and insurance combined.
2. Should I cancel my old endowment policy and buy term insurance instead?
Not without calculation. Check its surrender value, paid-up benefits, remaining premium term, bonuses and current insurance needs first. An old policy may sometimes be worth retaining while adding separate term cover.
3. Why does an endowment policy cost much more for the same life cover?
Because part of the premium supports savings, maturity benefits and other policy features in addition to life protection. A pure term plan mainly prices the mortality risk.
4. Can I take a loan against my endowment insurance policy?
Often yes once the policy has acquired the required surrender value. IRDAI currently requires eligible non-linked savings policies offering surrender value to provide a policy-loan facility, subject to the insurer’s terms.