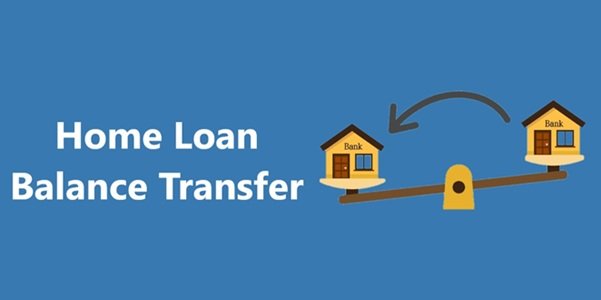
A home loan balance transfer allows a borrower to move the outstanding home loan from one bank or housing finance company to another. The main reason is usually a lower interest rate, but borrowers may also switch for a better repayment structure, improved service, a longer or shorter tenure, or access to an additional top-up loan.
A lower rate can produce substantial savings when a large principal amount and several years of repayment are still left. However, a balance transfer is not free. The new lender may charge processing, legal, valuation, mortgage-registration and other statutory costs. The existing lender may also have charges in situations where RBI’s prepayment protection does not apply.
For floating-rate home loans taken by individual borrowers for non-business purposes, RBI rules generally prohibit prepayment charges. The RBI’s updated Pre-payment Charges on Loans framework applies to loans sanctioned or renewed on or after January 1, 2026, while earlier protections also continue for qualifying existing floating-rate individual loans.
Therefore, before transferring a home loan, borrowers should calculate the net saving after every switching cost, not simply compare the old and new advertised interest rates.
What Is a Home Loan Balance Transfer?
A balance transfer means the new lender pays off the outstanding home loan with the existing lender.
After completion:
- The old loan is closed.
- The property’s mortgage documents are transferred or released as required.
- The borrower starts paying EMI to the new lender.
- The new lender creates its security over the property.
The borrower does not normally receive the transferred principal in cash because the amount is used to close the existing home loan.
If an additional top-up is approved, that extra amount may be disbursed separately.
Why Do Borrowers Transfer Home Loans?
The most common reasons are:
- Lower interest rate
- Lower EMI
- Shorter repayment tenure
- Lower total interest cost
- Better lender service
- Better digital facilities
- Conversion to a more suitable loan structure
- Additional top-up requirement
- More favourable repayment terms
The biggest potential benefit is usually interest saving.
How Much Can a Small Rate Difference Save?
Even a 0.50% to 1% rate reduction can matter when the outstanding principal is large.
Illustrative Example
Suppose:
- Outstanding home loan: ₹40 lakh
- Remaining tenure: 15 years
- Existing rate: 9%
- New rate: 8%
At 9%, the EMI is approximately:
₹40,571 per month
At 8%, it falls to approximately:
₹38,226 per month
Monthly reduction:
About ₹2,345
If both loans continue for the full remaining 15 years, the approximate interest saving is more than ₹4.2 lakh, before deducting transfer costs.
This is why even a one-percentage-point difference can be meaningful on a large, long-duration loan.
The example is illustrative. Actual savings depend on the exact outstanding amount, reset dates, interest method and tenure.
Main Costs of a Home Loan Balance Transfer
A borrower should consider all of the following before switching.
1. Processing Fee Charged by the New Lender
The new bank treats the transfer almost like a fresh loan application.
It may charge a processing fee for:
- Credit assessment
- Application processing
- Documentation
- Loan sanction
HDFC Bank currently lists balance-transfer processing charges for salaried and self-employed professional borrowers of up to 0.50% of the loan amount or ₹4,000, whichever is higher, plus applicable taxes. Its charges can be higher for some self-employed, NRI and specialised categories.
Axis Bank’s published home-loan charges currently provide for processing fees of up to 1% of the loan amount, subject to a minimum of ₹10,000, with applicable GST.
These are lender-specific maximum charges and can change. Promotional waivers are also common.
2. GST on Processing and Service Charges
GST is normally added to many lender service charges.
For example, if:
- Processing fee = ₹10,000
- GST rate applicable = 18%
The total becomes:
₹11,800
GST is not calculated on the loan principal itself. It applies to taxable banking services and specified fees.
3. Legal Verification Fee
The new lender does not simply rely on the old bank’s legal approval.
It may carry out a fresh check of:
- Title deeds
- Ownership chain
- Encumbrances
- Approved building plan
- Sale deed
- Other property records
Legal expenses may be included in the processing fee or charged separately.
HDFC Bank currently states that external legal or technical verification expenses may be charged on an actual basis where applicable.
4. Property Valuation Charges
The new lender may independently value the property before accepting it as security.
A technical valuer can examine:
- Property location
- Construction
- Age of building
- Market value
- Remaining economic life
- Plan compliance
This is particularly important if the borrower is also requesting a top-up.
The new bank is not required to accept the old lender’s valuation.
5. Mortgage and Registration Charges
Depending on the State and method used to create the mortgage, borrowers may have to pay:
- Memorandum of Deposit of Title Deeds charges
- Mortgage stamp duty
- Registration fee
- Franking charges
- Notary charges
These costs vary significantly between States.
HDFC Bank’s current balance-transfer fee schedule specifically states that stamp duty, MOD, MOE and registration charges apply according to the relevant State.
This can be one of the largest overlooked transfer expenses.
6. CERSAI Charges
Lenders register security interests with the Central Registry of Securitisation Asset Reconstruction and Security Interest of India, or CERSAI.
The new lender can recover the applicable statutory CERSAI fee.
For example, HDFC Bank currently lists CERSAI charges according to the actual regulatory fee, while Axis Bank publishes ₹50 for loans up to ₹5 lakh and ₹100 for loans above ₹5 lakh in its current schedule.
The amount is small compared with other transfer expenses but should still be included.
7. Foreclosure or Prepayment Charges
This is an area where borrowers should understand current RBI protections.
For qualifying floating-rate loans granted to individuals for non-business purposes, banks cannot levy prepayment charges under the applicable RBI framework.
For loans sanctioned or renewed from January 1, 2026, the RBI’s revised directions reinforce the prohibition.
Therefore, an individual transferring a standard floating-rate home loan generally should not face a foreclosure penalty merely because the new lender is paying off the existing loan.
When Can Charges Still Arise?
The position can differ for:
- Fixed-rate loans
- Certain business-purpose loans
- Non-individual borrowers
- Products outside the protected category
ICICI Bank’s current schedule, for example, lists nil prepayment charges on adjustable-rate home loans, while its fixed-rate home loans can attract a 2% prepayment charge under the stated conditions.
Always obtain a written foreclosure statement before transferring.
8. Document and Statement Charges
The old lender may charge small administrative amounts for certain optional or physical documents, depending on its schedule.
These can include:
- Loan account statement
- Repayment schedule
- Duplicate documents
- Physical prepayment statement
- Document copies
ICICI Bank currently lists ₹200 for certain physical statements, including a prepayment statement issued at a branch.
These charges are relatively small but can add to the total switching cost.
9. Insurance-Related Costs
A home loan transfer does not necessarily require the borrower to purchase a new insurance policy.
If an existing home or loan-protection policy is already in force, check whether it can continue or whether its assignment needs to be changed.
Do not automatically cancel an old policy and buy another without comparing:
- Remaining cover
- Refund value, if any
- New premium
- Policy conditions
Insurance purchases should be evaluated separately from the loan rate.
A Simple Balance Transfer Cost Breakdown
Suppose a borrower transfers ₹40 lakh.
Illustrative switching expenses might include:
| Expense | Illustrative Amount |
| Processing fee | ₹10,000 |
| GST on processing fee | ₹1,800 |
| Legal/technical verification | ₹5,000 |
| Mortgage/stamp-related expenses | ₹8,000 |
| CERSAI/other small statutory charges | ₹500 |
| Approximate total | ₹25,300 |
These figures are only examples. Actual State duties and lender charges can be considerably different.
If projected interest savings are ₹4 lakh while switching costs are ₹25,000, the transfer may look attractive.
If savings are only ₹30,000 while switching expenses total ₹25,000, the benefit may be too small to justify the effort.
Calculate the Break-Even Period
A useful way to decide is to calculate how long it takes for monthly EMI savings to recover the transfer cost.
Suppose:
- Total transfer cost: ₹30,000
- Monthly EMI saving: ₹2,500
Break-even period:
₹30,000 ÷ ₹2,500 = 12 months
If you plan to keep the loan for another 10 years, that may be attractive.
If you plan to sell the property six months later, the transfer probably makes little financial sense.
Lower EMI vs Shorter Tenure
After transferring to a lower interest rate, borrowers often have two choices.
Option 1: Reduce EMI
This improves monthly cash flow.
For example:
Old EMI: ₹40,500
New EMI: ₹38,200
The borrower saves approximately ₹2,300 every month.
Option 2: Keep EMI Almost Unchanged
Instead of reducing EMI, continuing roughly the old payment amount can help reduce the outstanding principal faster.
This can:
- Shorten tenure
- Reduce lifetime interest
- Create bigger overall savings
Borrowers whose monthly budget is comfortable may benefit more from shortening tenure rather than immediately lowering EMI.
When Is a Balance Transfer Most Beneficial?
A transfer is generally more attractive when:
- Outstanding principal is still large.
- Many years remain on the loan.
- New interest rate is materially lower.
- Credit score has improved.
- Transfer charges are low.
- Borrower intends to retain the property for several years.
It tends to provide the greatest benefit during the earlier or middle stages of a long home loan.
Why Transferring Near the End May Not Help Much
Home loan EMI consists of principal and interest.
During the early years, a relatively large portion of EMI goes toward interest.
Later, a larger share goes toward principal.
If only two or three years remain, the interest still payable may already be relatively small.
Even a lower rate may then fail to recover:
- Processing fee
- Mortgage charges
- Legal expenses
- Time and documentation effort
Always calculate the remaining interest rather than looking only at the original loan amount.
Can You Ask the Existing Bank to Reduce the Rate First?
Yes, and this can sometimes be cheaper.
Before transferring, ask the existing lender whether it offers an interest-rate conversion or spread reduction facility.
For example, HDFC Bank currently permits eligible variable-rate housing borrowers to switch to a lower rate for a conversion fee of up to 0.50% of principal outstanding and undisbursed amount, capped at ₹50,000, plus applicable taxes.
ICICI Bank currently lists a ₹3,000 conversion charge for specified floating-rate term-loan conversions.
If paying a small conversion fee gives nearly the same rate as the competing lender, staying with the existing bank can save legal and mortgage-transfer expenses.
Balance Transfer With Top-Up Loan
A new lender may also offer:
Home Loan Balance Transfer + Top-Up
This can be useful when the borrower requires additional money for:
- Renovation
- Education
- Medical expenses
- Other permitted purposes
However, do not transfer merely because the bank offers a large top-up.
Compare the interest rate and total repayment of the additional borrowing separately.
Documents Commonly Required
For a balance transfer, the new lender may ask for:
- PAN and Aadhaar
- Salary slips or business income documents
- Bank statements
- Existing home loan statement
- Repayment track record
- Foreclosure letter
- List of property documents held by existing lender
- Sale deed/title documents
- Approved plan
- Property tax records where applicable
- Other legal and technical documents
The new bank conducts a fresh credit, legal and technical assessment. A balance transfer is therefore not automatically approved simply because another bank previously sanctioned the loan.
What Happens to Original Property Documents?
When the existing loan is closed, the old lender must release the property documents and complete the relevant charge-release procedures.
RBI rules require regulated lenders to release original movable or immovable property documents and remove registered charges within 30 days after full repayment or settlement of a personal loan. If a delay beyond the prescribed period is attributable to the lender, compensation of ₹5,000 per day applies.
In a balance transfer, lenders commonly coordinate document movement as part of the takeover process.
FAQs
1. How much interest-rate difference is enough to justify a home loan transfer?
There is no universal minimum. Even a 0.50% difference may be worthwhile when the outstanding principal is large and many years remain. Calculate total future savings after deducting all switching costs.
2. Can my existing bank charge foreclosure fees if I transfer my floating-rate home loan?
For a qualifying floating-rate home loan to an individual for non-business purposes, RBI rules prohibit prepayment charges. Fixed-rate and other excluded loan categories can have different rules.
3. Should I reduce EMI or tenure after transferring?
If monthly affordability is not a problem, maintaining a similar EMI and reducing the tenure can usually produce greater lifetime interest savings. Lowering EMI is useful when improving monthly cash flow is the priority.
4. Can a balance-transfer application be rejected even if my existing loan is regular?
Yes. The new lender performs its own income, credit, legal and property assessment. Changes in income, poor credit history, property-document problems or inadequate valuation can lead to rejection.